
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be considered financial, investment, tax, or legal advice. Always do your own research or consult a professional before making financial decisions.
Introduction
Debt can feel like a pile that never shrinks. You pay every month, the balances barely move, and the biggest loan always seems to sit there mocking you. If that sounds familiar, the problem may not be your effort — it may be the order you are paying things off in.
The debt snowball method flips the usual logic on its head. Instead of chasing interest rates, you chase wins: smallest balance first, then the next, then the next. It is simple, beginner-friendly, and it works because it keeps you motivated long enough to finish.
This guide explains what the debt snowball method is, walks you through setting one up step by step, shows a real example of it in action, and compares it with the debt avalanche method so you can pick the approach that fits you best.
What Is the Debt Snowball Method?

The debt snowball method is a repayment strategy built on one rule: clear your debts from the smallest balance to the largest, whatever the interest rates say. You keep paying the minimum on every debt, but every spare dollar goes at the smallest one until it is gone.
Once that first debt is cleared, you take the money you were paying on it and add it to the minimum payment of the next-smallest debt. The payment grows with every debt you knock out — that is the snowball effect.
Financial personality Dave Ramsey popularized the method, and it has stayed popular for a good reason: it suits people who feel buried by debt and need early wins to stay on track.
Why the Debt Snowball Works (Even Without Saving on Interest)
On paper, paying the highest-interest debt first — the debt avalanche method — saves you more money over time. So why do so many people pick the snowball instead?
Because personal finance is personal. Research in behavioral finance keeps finding the same thing: people stick with a payoff plan when they can see fast, visible progress. Clearing a small $300 balance in your first month feels like a genuine win, and that win builds the confidence to keep going — even when it is not the mathematically “optimal” choice.
Put simply, the debt snowball trades a little potential interest saving for a much better chance that you actually finish paying everything off.
Step-by-Step: How to Set Up Your Debt Snowball
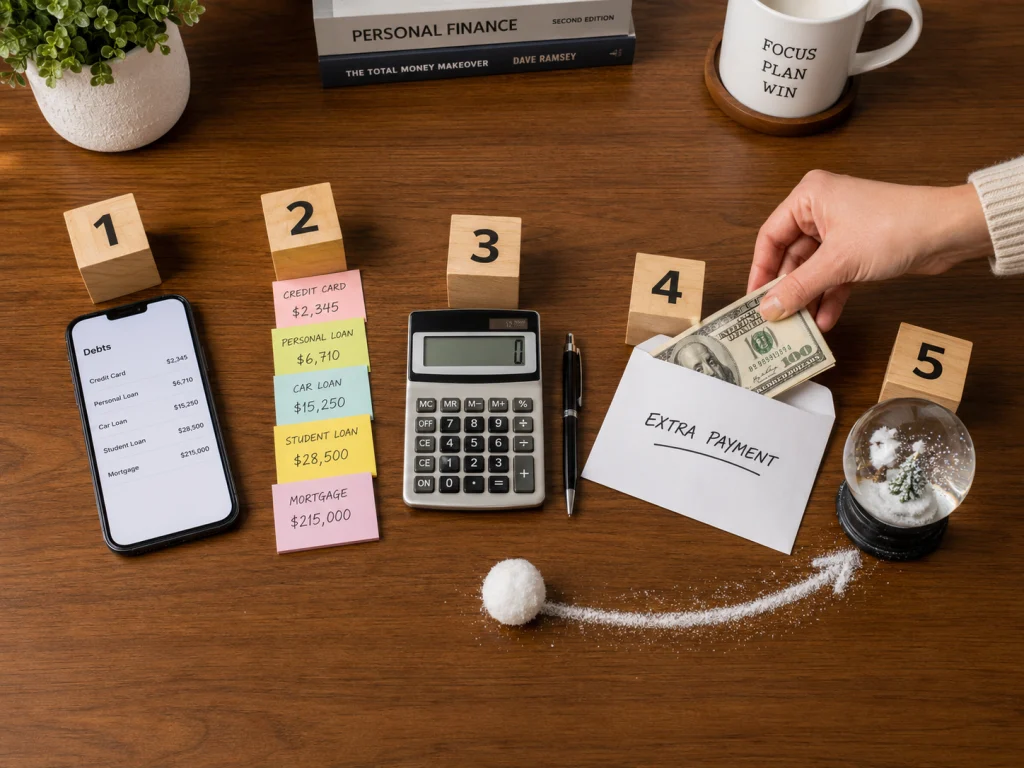
Step 1: List All Your Debts
Write down every debt you owe — credit cards, personal loans, medical bills, car loans, student loans. For each one, note:
- The creditor name
- Total balance owed
- Minimum monthly payment
- Interest rate (for reference, not for ordering)
Step 2: Order Debts From Smallest to Largest Balance
Forget interest rates for now. Just rank your debts from the smallest balance to the biggest. That order is the backbone of your snowball.
Step 3: Pay Minimums on Everything Except the Smallest Debt
Keep making at least the minimum payment on every debt, so you avoid late fees and damage to your credit score. Everything extra goes to the smallest debt.
Step 4: Attack the Smallest Debt With Extra Money
Find any spare money in your budget — from cutting expenses, a side hustle, or a no-spend challenge — and throw it all at your smallest debt until it is paid off.
Step 5: Roll the Payment Into the Next Debt
Once the smallest debt is gone, roll everything you were paying on it — the minimum plus the extra — into the next-smallest debt. Repeat until every debt is cleared.
A Simple Example
Let’s say you have three debts:
| Debt | Balance | Minimum Payment |
|---|---|---|
| Store Credit Card | $500 | $25 |
| Personal Loan | $2,000 | $75 |
| Car Loan | $6,000 | $200 |

If you have an extra $150 a month to put toward debt, here’s how the snowball plays out:
- You pay $25 (minimum) + $150 (extra) = $175 toward the store credit card. It’s paid off in about 3 months.
- That $175 now rolls into the personal loan payment: $75 + $175 = $250/month. The loan gets paid off much faster than making minimum payments alone.
- Once the personal loan is cleared, that full $250 rolls into the car loan, on top of its $200 minimum — now you’re paying $450/month toward the last debt.
By the time you reach your last debt, you are attacking it with real momentum — even though the extra amount you started with never changed.
Debt Snowball vs. Debt Avalanche: Which Should You Choose?
| Factor | Debt Snowball | Debt Avalanche |
|---|---|---|
| Payoff order | Smallest balance first | Highest interest rate first |
| Best for | Motivation and momentum | Saving the most money on interest |
| Speed of first “win” | Fast | Can be slow if highest-interest debt has a large balance |
| Total interest paid | Slightly higher | Lower |
Choose the debt snowball if you have struggled to stick with payoff plans before, or you need quick wins to keep yourself motivated.
Choose the debt avalanche if you are comfortable with numbers and want to pay as little interest as possible overall, even if the first debt takes longer to clear.
There is no wrong answer here — the best method is the one you will actually stick with.
Tips to Make Your Debt Snowball Work Faster

- Free up extra cash first. Pair your snowball with a short savings challenge or by trimming a few recurring subscriptions.
- Automate minimum payments. This protects your credit score while you focus your energy on the target debt.
- Track your progress visually. A simple chart or app that shows your shrinking debt list can keep motivation high.
- Avoid taking on new debt while you’re in the middle of your snowball — this can undo your progress quickly.
- Celebrate small wins. Paying off even a small debt is real progress worth acknowledging.
Final Thoughts
The debt snowball method is not about paying debt off in the most mathematically efficient way. It is about building a system you can actually stick with until you are debt-free. Start small, collect quick wins, roll your payments forward, and the momentum carries you even when the finish line feels a long way off.
Not sure where to start? Grab a notebook or a spreadsheet today, list your debts from smallest to largest, and take the first step. A sinking fund for irregular bills can also stop new debt creeping back while you work through the list. Progress — not perfection — is what gets you out of debt for good.
The debt snowball is Baby Step 2 in Dave Ramsey’s The Total Money Makeover — the book that made this method famous.