Disclaimer: The information provided in this article is for educational and informational purposes only and should not be considered financial, investment, tax, or legal advice. Always do your own research or consult a professional before making financial decisions.
Introduction
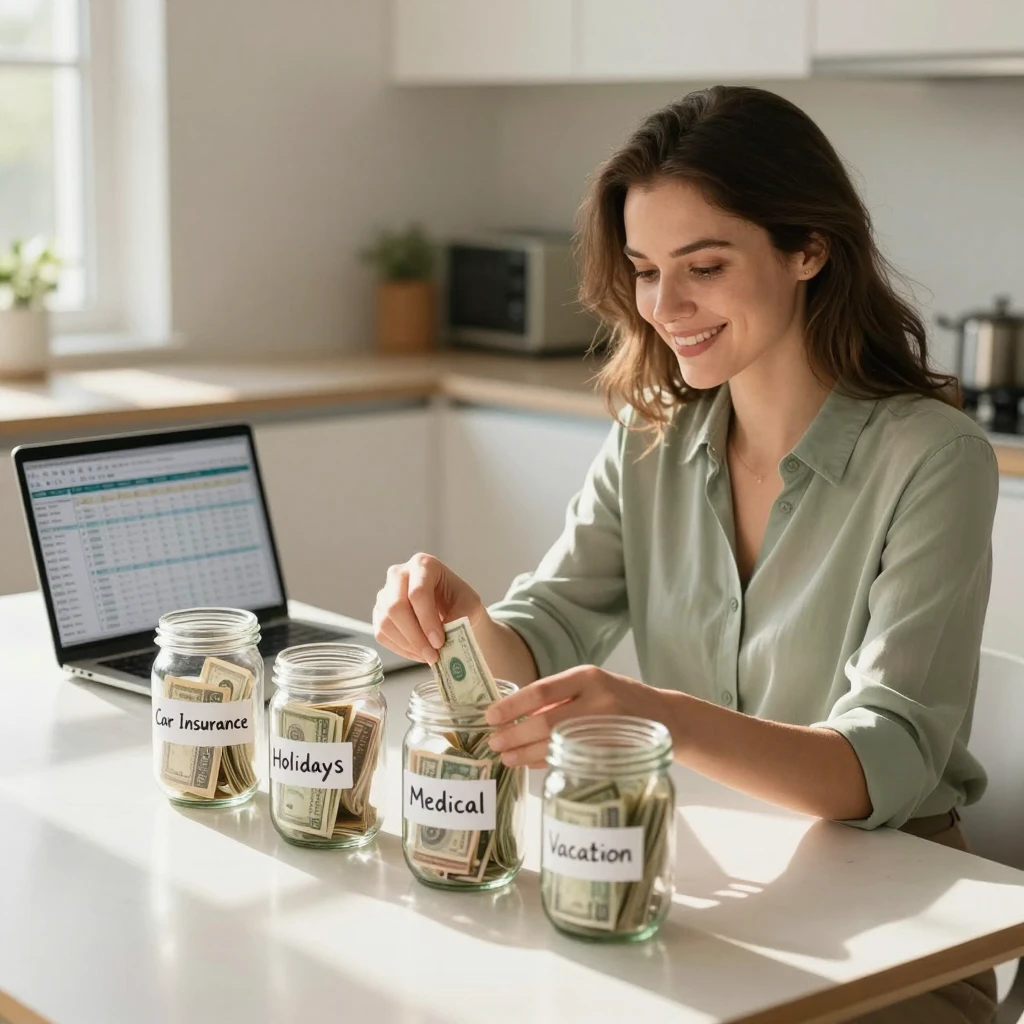
Some bills pretend to be surprises. Your car insurance renewal, back-to-school shopping, an annual subscription charge, the yearly dentist visit — they all arrive on schedule, yet somehow they still knock your budget sideways every single time.
That is exactly the problem a sinking fund is built to fix.
An emergency fund covers the genuinely unexpected. A sinking fund is different: it is for the expenses you already know are coming. It may be one of the most underrated budgeting tools around, and once you have one in place, those “surprise” bills stop being a scramble.
This guide explains what a sinking fund is, how it differs from an emergency fund, how to set one up step by step, and which categories are worth starting with.
What Is a Sinking Fund?
A sinking fund is simply money put aside bit by bit for one specific expense you know is on its way. Rather than paying a large bill all at once and feeling the pinch, you spread it into smaller, manageable amounts saved over weeks or months.

Say your car insurance costs $600 every six months. Put $100 a month into a “Car Insurance” sinking fund, and when the bill lands, the money is already waiting — no stress, no credit card debt, and no raiding your emergency fund.
Sinking Fund vs. Emergency Fund: What’s the Difference?
People mix these two up all the time, but they do very different jobs.
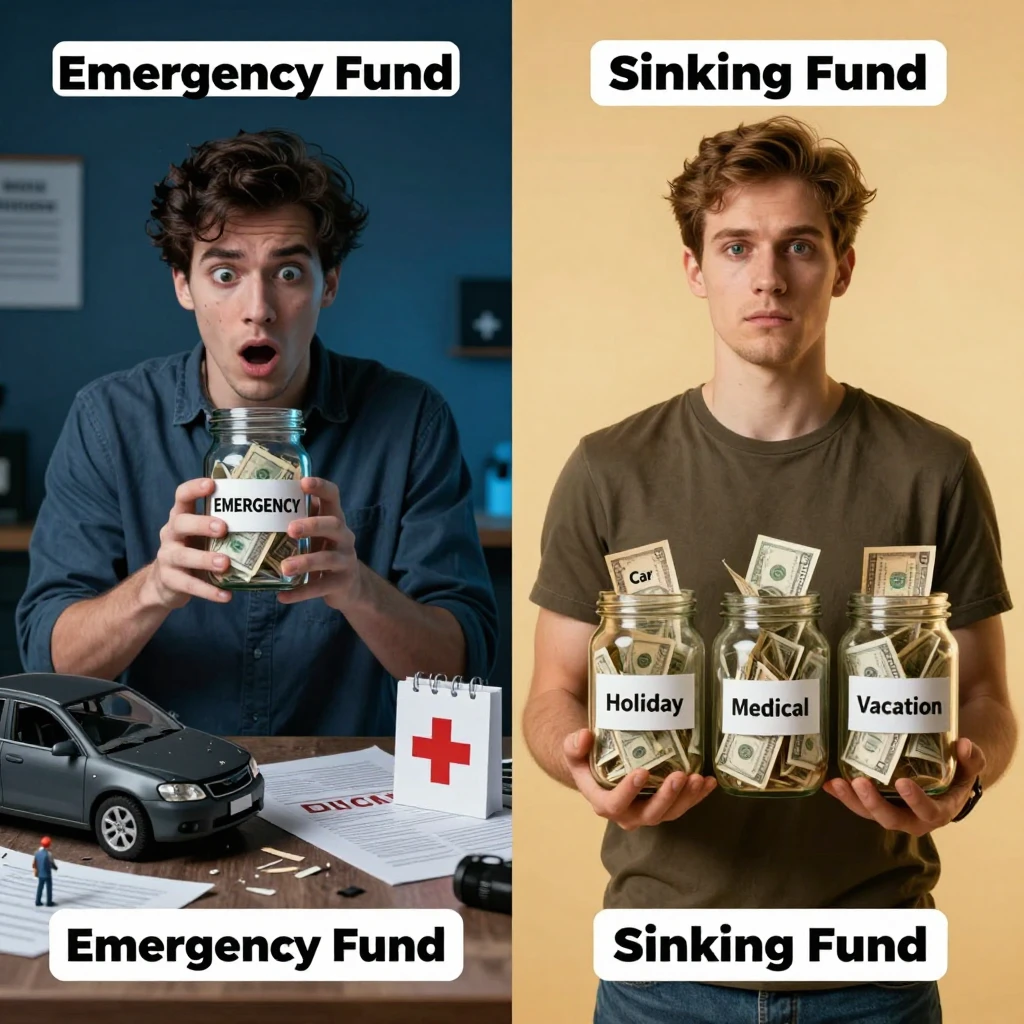
| Feature | Sinking Fund | Emergency Fund |
|---|---|---|
| Purpose | Planned, known future expenses | Unexpected emergencies |
| Examples | Car registration, holiday gifts, vacations | Job loss, medical emergency, major car repair |
| Predictability | Known amount and timing | Unknown amount and timing |
| Number of funds | Multiple, one per category | Usually just one |
Put it this way: your emergency fund is the safety net for the unknown, while your sinking funds are the plan for the known. Used together, they are what real financial stability looks like.
Why You Need a Sinking Fund

- It stops “surprise” expenses from becoming debt. Many people rely on credit cards for irregular expenses simply because they didn’t plan ahead. A sinking fund removes that temptation.
- It protects your emergency fund. Without sinking funds, people often raid their emergency savings for predictable costs like car maintenance or holiday shopping leaving them exposed when a real emergency hits.
- It reduces financial stress. Knowing the money is already set aside for that annual bill means one less thing to worry about.
- It works with any budgeting method. Sinking funds pair especially well with cash stuffing and envelope budgeting systems.
How to Set Up a Sinking Fund (Step-by-Step)
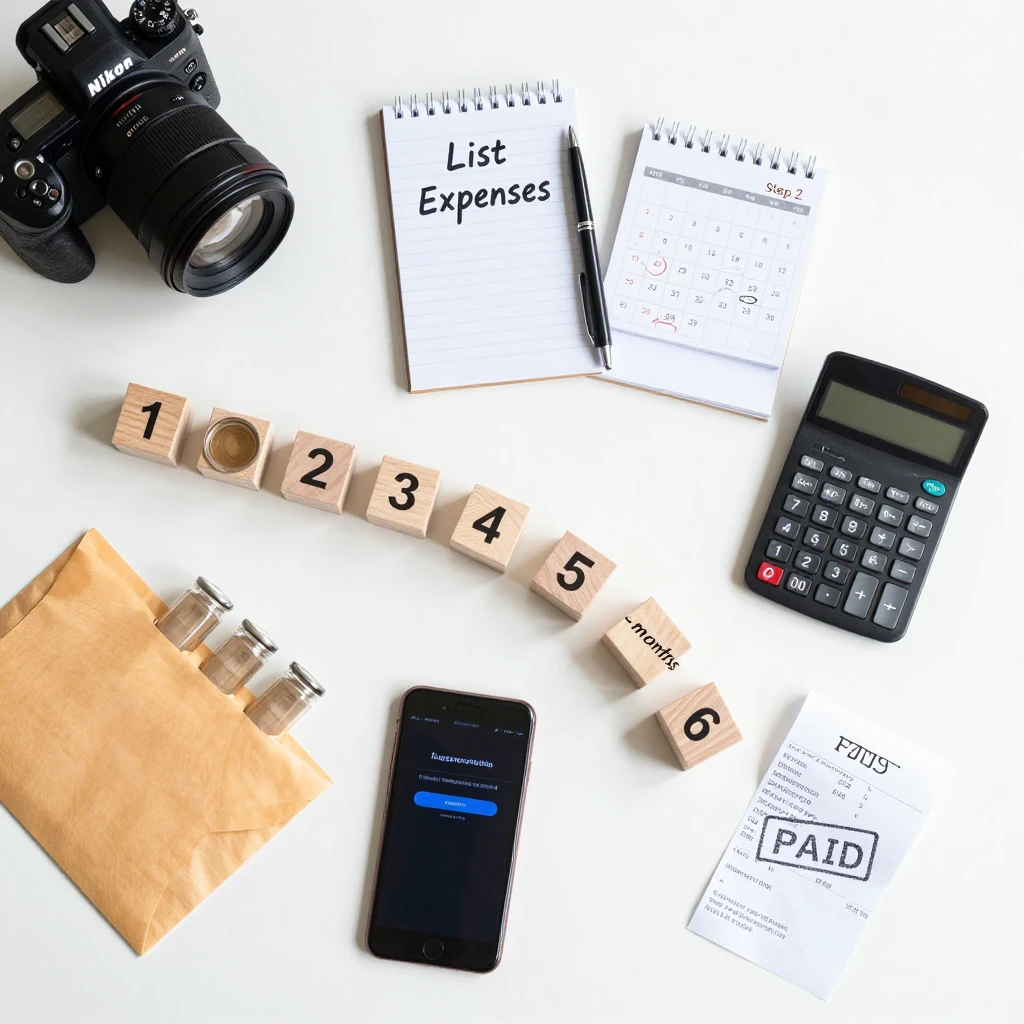
Step 1: List Your Irregular Expenses
Look back over the last 12 months of spending — bank statements are perfect for this — and note every expense that does not come round monthly.
Step 2: Estimate the Cost and Timing of Each
Beside each one, jot down roughly what it costs and when it is due. If you are not certain of the figure, round it up a little; a small buffer beats a shortfall.
Step 3: Divide the Cost by the Months Until It’s Due
That gives you the monthly amount to save. A $600 car insurance bill due in six months, for instance, means $100 a month.
Step 4: Open Separate Savings “Buckets”
Cash envelopes work, so does a spreadsheet, and so does a savings account that lets you split money into sub-accounts or labelled pots. The method matters less than keeping each fund separate.
Step 5: Automate or Schedule Your Contributions
Set up a recurring transfer, or fold the contributions into your regular cash-stuffing routine, so you do not have to think about them every month.
Step 6: Use It (and Refill It)
When the bill arrives, pay it straight from the fund. Then start building that category back up again, ready for next time.
Sinking Fund Categories List
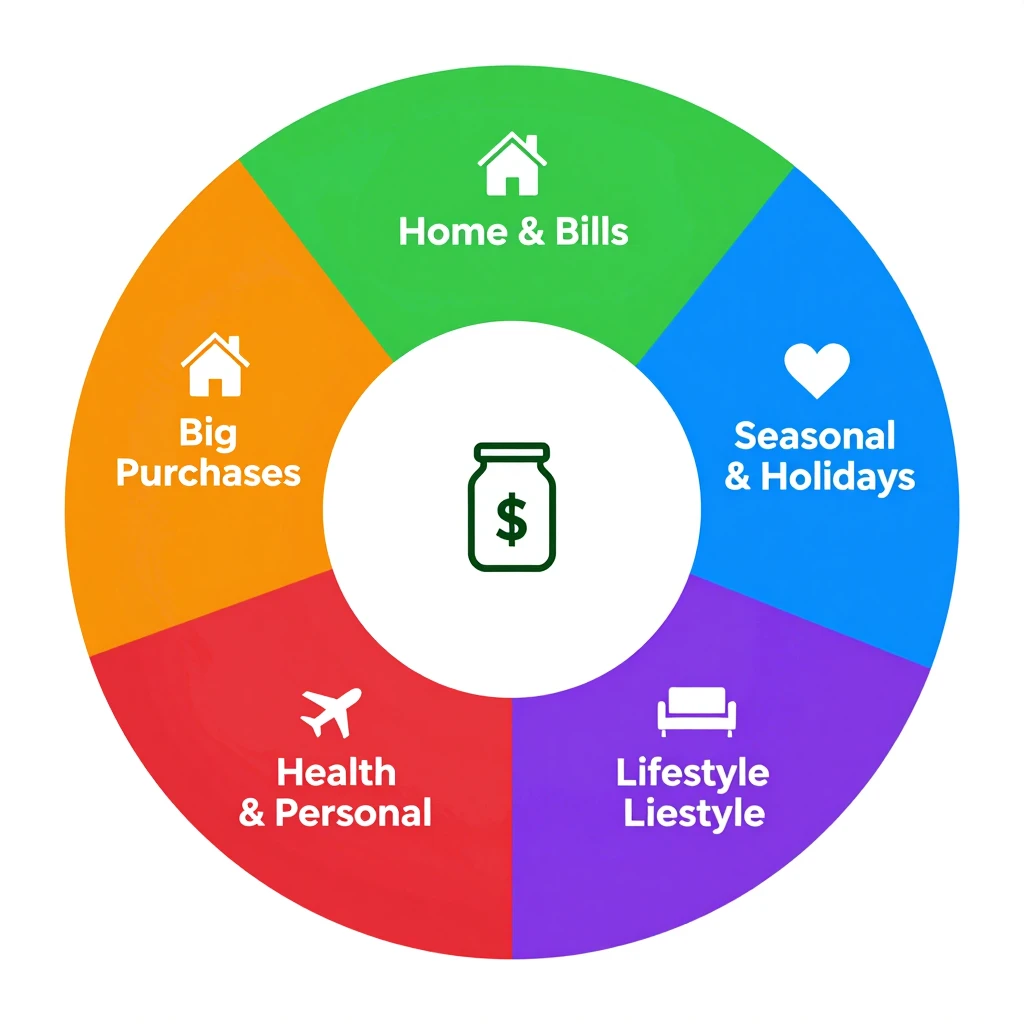
Not sure where to begin? These are the categories most people start with. If your budget is already stretched, picking up some side hustle ideas can help you fund them faster.
Home & Bills
- Car registration/renewal
- Car insurance (if paid in a lump sum)
- Car maintenance and repairs
- Home maintenance/repairs
- Property taxes
- Annual subscriptions (streaming, software, memberships)
Seasonal & Holidays
- Christmas/holiday gifts
- Birthdays
- Back-to-school supplies
- Summer camp or activities
Health & Personal
- Medical/dental copays
- Prescriptions
- Pet care and vet visits
Lifestyle
- Vacations/travel
- Clothing (seasonal wardrobe changes)
- Gifts (weddings, baby showers, etc.)
Big Purchases
- New appliances
- Electronics upgrade
- Furniture
You do not need to tackle all of these at once. Start with the two or three that have caused you the most financial strain in the past.
Tips for Making Sinking Funds Work Long-Term
- Start small. Even $10–$20 a month per category adds up faster than you think.
- Review and adjust every few months. Costs change, and so should your sinking fund amounts.
- Label everything clearly. Whether it’s cash envelopes or a digital spreadsheet, clear labels prevent you from accidentally spending one category’s money on another.
- Pair it with a no-spend challenge to free up extra cash to jumpstart your sinking funds faster.
- Celebrate hitting a goal. When a sinking fund is fully funded, that’s real progress — acknowledge it.
Final Thoughts

That is what a sinking fund does: it turns “surprise” expenses into planned ones. Instead of scrambling when an irregular bill lands, the money is already set aside and ready. Start with just one or two categories this month, and notice how much lighter your budget feels once those surprises stop catching you off guard.
Already doing cash stuffing or a no-spend challenge? Sinking funds slot right in — they are the natural next step toward a budgeting system that actually works in real life.