
Introduction
If the word budget makes you think of dull spreadsheets and giving up everything you enjoy, you are not alone. I used to feel exactly the same way, and for a long time that feeling kept me from even trying.
For years I did the same thing: I built a complicated spreadsheet, tracked every purchase for a week, felt overwhelmed, and quit. Then I would wonder, again, where all my money had gone.
What finally changed my mind was a simple shift: budgeting is not about restriction. It is about freedom, because a plan lets you choose what your money is for instead of guessing at the end of the month.
A good budget does not tell you what you cannot do. It shows you what you can do, and it gives you permission to spend on what matters because you have planned for it. That is the difference between feeling guilty about money and feeling calm about it.

After a lot of trial and error, I settled on a much simpler approach, and that is what this guide shares: 20 practical tips that actually work in real life, not just on paper.
Some of these tips take five minutes, and some will change how you think about money. You do not need to use all 20 at once. Start with one, see how it feels, and build from there.
Part 1: Mindset & Getting Started
1. Know Your “Why” Before You Start
Most people skip this question: Why do you want a budget?

Not the surface answer. The real one. Maybe you want to stop stressing about bills. Or you want to save for a house, pay off debt, or finally take that trip. Maybe you just want to stop fighting with your partner about money.
Whatever it is, write it down. Put it on your fridge. Make it your phone wallpaper. See it every day.
Here’s why: budgeting is hard when it’s just numbers. But when it’s connected to something you truly want, it becomes meaningful. That “why” keeps you going when you feel like giving up.
I had “DEBT FREEDOM 2025” on my bathroom mirror for two years. Every morning, I saw it. It reminded me why I was saying no to some things now, so I could say yes to bigger things later.
2. Track First, Budget Second

Most people do this backward. They try to create a budget without knowing where their money actually goes. That’s like trying to lose weight without ever stepping on a scale.
Don’t jump straight into making a budget. First, spend a week or two just watching where your money goes. No judgment. No restriction. Just awareness.
Use a notebook, your phone’s notes app, or just scroll through your bank statements. Track everything—coffee, takeout, Amazon purchases, subscriptions.
At the end of the week, look at the patterns. What surprised you? This isn’t about beating yourself up. It’s just gathering information. And information is power. You can’t fix what you don’t measure.
3. Start with the “Three-Bucket” System
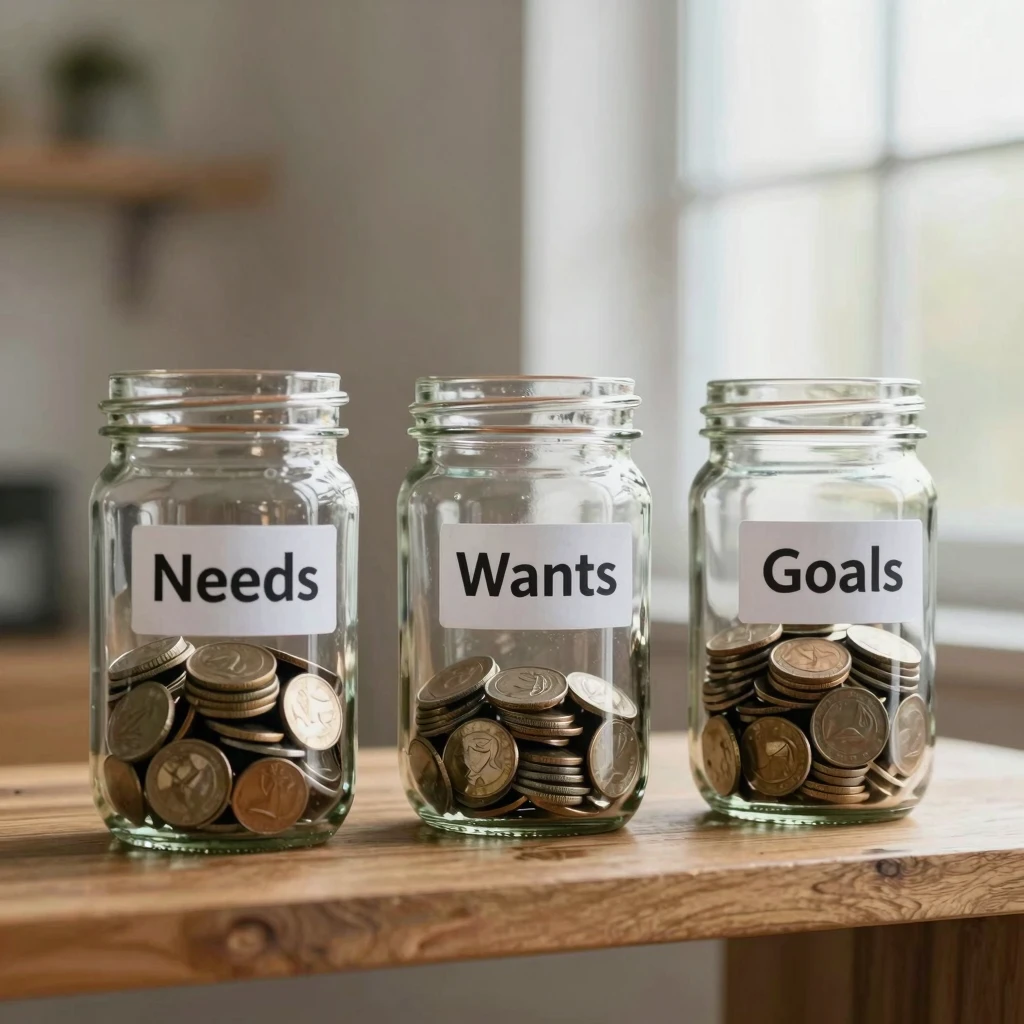
Forget complicated categories with 20 different line items. That’s overwhelming. Start with just three buckets:
Needs: Rent, groceries, utilities, minimum debt payments, insurance, transportation.
Wants: Dining out, entertainment, shopping, hobbies, streaming services, vacations.
Goals: Savings, extra debt payments, investments, emergency fund.
Look at your monthly income and split it into these three buckets. A common starting point is 50% needs, 30% wants, 20% goals.
But here’s the thing: it’s just a starting point. If your needs cost more than 50%, adjust by taking from wants. The percentages can flex. The important part is that you’re thinking in three simple buckets instead of getting lost in dozens of tiny categories.
4. Don’t Aim for Perfection
Here’s something they don’t tell you: your first budget will be wrong. And that’s totally fine.
You’ll underestimate some categories. Some expenses will slip your mind. You’ll mess up.
The goal isn’t a perfect budget on the first try. The goal is to start, learn, and adjust. Treat it like an experiment, not a test. You’re gathering data. You’re learning about your own habits.
Then you tweak and try again. It usually takes about three months to really get the hang of it. Three months of adjusting, learning, and refining. So be patient with yourself. You’re building a skill, and skills take time. Perfection is the enemy of progress.
5. Use the 50/30/20 Rule as Your Compass
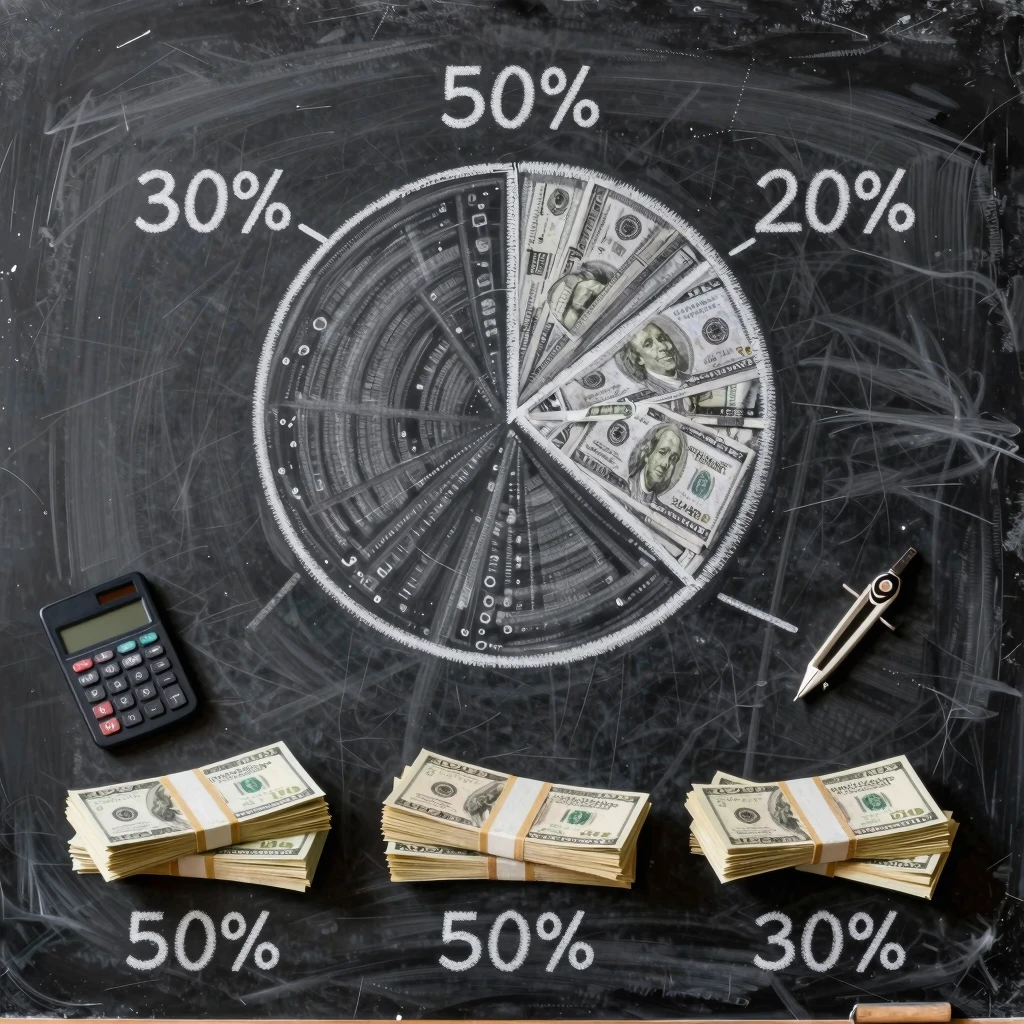
If you have no idea where to begin, the 50/30/20 rule is your best friend. It’s simple, proven, and works for most people.
Here’s how it breaks down with a real example. Let’s say you take home $3,000 per month after taxes.
50% ($1,500) goes to needs: rent, groceries, utilities, minimum debt payments, transportation.
30% ($900) goes to wants: dining out, entertainment, hobbies, shopping, fun stuff.
20% ($600) goes to goals: savings, extra debt payments, investments.
That’s it. Three numbers. If your needs are higher than 50%, adjust by shrinking wants. The beauty of this system is that it gives you permission to spend on wants without guilt. As long as needs are covered and goals are funded, that 30% is yours to enjoy. No guilt. No stress.
Part 2: Building Your Budget
6. Try Zero-Based Budgeting

Zero-based budgeting sounds complicated, but it’s simple: every dollar has a job.
At the start of the month, take your income and assign every single dollar to a category until your income minus expenses equals zero. This doesn’t mean you spend everything. It means you’re intentional.
Every dollar is either paying bills, going to savings, set aside for future expenses, or allocated for fun. Nothing is just “left over” to disappear on random stuff you won’t remember next week.
The magic of this system is that it forces you to be intentional. You’re not hoping money will be left at the end of the month. You’re telling every dollar exactly where to go. It’s empowering and eye-opening.
7. Or Try the Reverse Budget

If tracking every dollar feels exhausting, try the “pay yourself first” method. It’s the opposite of zero-based budgeting, and for some people, it works way better.
Here’s how it works: as soon as you get paid, automatically move money to savings and investments. Pay yourself first, before anything else.
Then pay your essential bills—rent, utilities, minimum debt payments. Whatever is left after that? Spend it guilt-free on whatever you want.
No complicated tracking. No categorizing every coffee run. As long as your savings goals are met and bills are paid, you can spend the rest without stress. This works because it removes guilt and mental load.
8. Use the Envelope System for Problem Categories

If you have specific categories where you always overspend—like eating out, shopping, or entertainment—try the envelope system. It sounds old-school, but it works because it’s visual and physical.
Here’s how: withdraw cash for that category at the start of the month. Put it in an envelope labeled “Eating Out” or “Shopping” or whatever.
When you want to spend from that category, use cash from the envelope. When the cash is gone, you’re done spending there for the month. No exceptions. No “just this once.”
The psychology behind this is powerful. When you use a card, it doesn’t feel like real money. You tap and forget. But when you physically hand over cash and watch your envelope get thinner, you think twice before spending.
9. Don’t Forget Irregular Expenses

This is where most budgets fail. They account for monthly stuff but completely forget about expenses that hit once or twice a year.
You remember rent. You remember your phone bill. But do you remember:
- Car insurance due every six months?
- Annual subscriptions like Amazon Prime?
- Holiday and birthday gifts?
- Car registration and maintenance?
- Vet visits for your pet?
These expenses sneak up on you every single time. The solution? Create sinking funds. A sinking fund is just saving a little each month for expenses you know are coming.
Add up all your irregular expenses for the year, divide by 12, and save that amount monthly in a separate account. When the bill comes, the money’s ready. No stress. No budget blowouts.
10. Budget for Fun (Seriously, This Matters)

If your budget doesn’t include any money for things you enjoy, you will not stick to it. I cannot emphasize this enough.
Humans need fun. We need dinners out, movies, concerts, hobbies, treats, and spontaneous adventures. We are not machines designed to optimize every dollar. We’re people who need joy.
When you cut all of that out, your brain rebels. You’ll last two weeks being “perfect,” then you’ll binge-spend and feel guilty. Then you’ll quit budgeting altogether because it “doesn’t work.”
So put “fun money” in your budget. Guilt-free money you can spend on whatever you want, no questions asked. Maybe it’s $50 a week. Maybe it’s $200 a month. Whatever fits your situation.
This isn’t a luxury. It’s a necessity for long-term success. A budget that includes fun is a budget you’ll actually stick with.
Part 3: Sticking to Your Budget
11. Automate Everything You Can

Willpower is overrated. Seriously. It’s a limited resource that runs out by the end of the day. That’s why you’re more likely to order takeout at 8pm than at 8am.
Automation is the hack. When money moves automatically, you don’t have to make decisions. You don’t have to remember. You don’t have to exercise willpower.
Set up automatic transfers for savings right after payday, before you can spend the money. Set up autopay for bills so you never miss a due date and never pay late fees. Automate extra debt payments so you’re consistently making progress.
When you automate, you “set it and forget it.” Your savings grow, bills get paid, and you don’t have to think about it. It’s the closest thing to magic in personal finance.
12. Have Weekly “Money Dates”

Set aside 15 minutes once a week to check in with your budget. I call these “money dates.”
During your money date, look at what you’ve spent this week. Check if you’re on track for the month. Adjust categories if needed. Celebrate your wins and learn from your mistakes.
It’s not about beating yourself up if you overspent. It’s just staying aware. A quick weekly check prevents nasty surprises at the end of the month when it’s too late to adjust.
Pick a consistent time that works for you. Sunday morning with coffee. Friday afternoon before the weekend. Whatever fits. Put it on your calendar. Make it a habit. Fifteen minutes a week saves hours of stress later.
13. Use the Right Tools for You

You don’t need complicated spreadsheets if they stress you out. Use whatever tool you’ll actually use consistently.
Options include apps like EveryDollar, YNAB (You Need A Budget), or Goodbudget. These automate a lot of the tracking work.
Spreadsheets work great if you enjoy Excel or Google Sheets. You can customize everything exactly how you want.
Pen and paper is totally fine too. My grandmother tracked her budget in a notebook for 40 years.
If you like writing things down, a written monthly budget planner such as the Clever Fox Budget Planner can give you that same simple structure, month after month.
It’s not about the tool. It’s about consistency.
Many banking apps now have built-in budgeting features. Check what your bank offers. The best tool is the one you’ll actually use—not the one that looks impressive.
14. Give Yourself Grace
You will have months where you blow your budget completely. It happens to everyone. Seriously, everyone.
Maybe there was a wedding, a birthday, an emergency, or just a week where you needed takeout every night because life was hard. It’s okay. You’re human.
The key is what you do next. Instead of quitting and saying “budgeting doesn’t work,” ask yourself:
- What happened?
- What can I learn from this?
- How can I adjust for next time?
Maybe you need a bigger “miscellaneous” category. Planning better for events could help, too. Maybe you just need to accept that some months are expensive and move on.
One bad month doesn’t ruin your financial life. Quitting does. So give yourself grace, learn, and keep going.
15. Find a Budget Buddy

Accountability helps more than you’d think. Find a friend, partner, or online community to check in with.
Share your wins and your struggles. Talk about what’s working and what’s hard. Having someone in your corner makes it easier to stay motivated.
You’re not alone in this. We’re all figuring it out as we go. There are great communities on Reddit like r/personalfinance and r/budget. Facebook has groups. Discord has servers.
Find your people. Sometimes just knowing someone else is on the same journey makes all the difference. You can encourage each other, share tips, and celebrate progress together.
Part 4: Cutting Costs Without Feeling Miserable
16. Audit Your Subscriptions Regularly

This is the easiest money you’ll ever save. The average person spends $50 to $100 a month on subscriptions they forgot about.
Streaming services, gym memberships, apps, subscription boxes, clubs—they add up quietly. Every three months, go through your bank statements. Find every recurring charge.
Ask yourself one question: Did I use this in the last 30 days? If the answer is no, cancel it. Takes two minutes. Saves hundreds a year.
Companies count on you forgetting. It’s literally part of their business model. Don’t let them win. Set a reminder on your calendar for every 90 days. Make it a habit. Future you will thank you.
17. Meal Plan Even Just a Little

Food is one of the biggest budget busters. Not because food is expensive, but because unplanned food is expensive.
You don’t need to meal prep 21 meals a week like those Instagram influencers. Just plan a few days ahead.
On Sunday, think about the week ahead. What’s for dinner Monday? Tuesday? Maybe Wednesday? Write it down. Get what you need from the store.
When you know what’s for dinner, you’re way less likely to order takeout because you’re tired and hungry and don’t know what else to do. Even a loose plan saves money. Start with just two or three planned dinners a week.
18. Brown-Bag Your Lunch Sometimes

Eating out for lunch every day adds up faster than you’d think. Let’s do the math together:
$15 per day times 5 days equals $75 per week. $75 per week times 4 weeks equals $300 per month. $300 per month times 12 months equals $3,600 per year.
That’s a vacation. That covers debt payments. That’s serious money.
I’m not saying never eat out. But bringing lunch from home just two days a week saves over $1,400 a year. That’s painless savings.
Pack leftovers from dinner. Make an extra sandwich in the morning. It takes five minutes. Your wallet will thank you. And honestly? Homemade lunch is often healthier too.
19. Review Your Big Bills Annually

When’s the last time you checked your insurance rates? Your phone plan? Your internet bill?
Here’s the thing: companies raise prices slowly over time. You probably didn’t notice. But competitors want your business. They’ll give you better rates to switch.
Once a year, take an hour to shop around. Check car insurance, home or renter’s insurance, your phone plan, internet service.
People who shop around for car insurance save an average of $600 a year. That’s $600 for one hour of work. Best hourly rate you’ll ever get.
Put a reminder on your calendar. Make it a yearly habit. It’s boring, but it pays.
20. Pause Before Every Non-Essential Purchase

This one simple habit saves more money than anything else. Before buying anything that’s not a true necessity, pause for 30 seconds.
Ask yourself these questions:
- Do I really need this?
- Will I use it next week? Next month?
- Where will I put it?
- Is there a cheaper option?
- Would I rather have the money instead?
Just a 30-second pause gives your brain time to think instead of impulse-spend. Half the time, you’ll realize you don’t really want it.
The urge passes. The money stays in your pocket. This single habit can save you hundreds of dollars a year without any real effort.
How to Actually Start (Without Burning Out)

Here’s where most people mess up: they read articles like this, get excited, and try to do everything at once.
Track every expense. Cut all spending. Automate everything. Start three different budgeting methods at the same time. Create a color-coded spreadsheet with 50 categories.
Then they burn out in two weeks and go back to old habits.
Don’t be that person. Pick one tip from this list. Just one.
Maybe it’s tracking your spending for a week. It could be setting up automatic savings. Maybe it’s canceling forgotten subscriptions. Maybe it’s starting a sinking fund.
Do that one thing for 30 days. Make it a habit. Make it automatic. Then pick another one.
Slow and steady wins the race. Consistency beats intensity every single time. One habit at a time, you’ll build a system that actually works.
Conclusion: A Budget Is Just a Tool
Here’s the thing I want you to remember above all else:
A budget isn’t a prison. It’s not a report card. It’s not a way to judge yourself or feel guilty about being human.
A budget is just a tool. A tool that helps your money go where you actually want it to go.
Without a budget, money leaks. It disappears on things you don’t remember and don’t care about. You work hard, and at the end of the month, you have nothing to show for it. Then you stress about bills. You avoid looking at your bank account. You feel out of control.
With a budget? You’re in control. You decide where every dollar goes. You spend on what matters, save for what’s important, and stop feeling guilty about the rest. Sleep comes easier at night. You have options.
That’s not restriction. That’s freedom.
The Bottom Line
Look, I’m not perfect with money. I still have months where I overspend. I still order takeout when I’m tired. Sometimes I still buy things I don’t really need.
But these tips? They keep me from going off the rails. On my weakest days, they save me from myself. They make sure that even when I mess up, I’m still moving forward. Still making progress. Still building toward something.
Nobody needs to be a finance expert. You don’t need to track every single penny. You don’t need to give up everything you love.
What you really need is a system that works for you. Simple, flexible, forgiving. That’s it.
Start with one tip from this list. Just one. Try it for a month. See how it feels.
Your future self—the one who sleeps peacefully, who doesn’t panic when bills come due, who actually knows where their money went, who has options and choices and freedom—that version of you is waiting.
And they’re cheering for you.
Keep reading: if these tips helped, these guides go deeper on the same ideas.
How to Create a Monthly Budget
50/30/20 Budget Rule Explained: The Simple Way to Manage Your Money
Sinking Fund Explained: How to Save for Irregular Expenses
You got this.
Frequently Asked Questions
Start with the three-bucket system: split your income into needs, wants, and goals, using the 50/30/20 rule as a starting point. If your needs cost more than 50%, adjust by shrinking wants.
It usually takes about three months. Your first budget will be wrong, and that is fine. Start, learn, and adjust each month until the habit sticks.
Do not quit. Ask what happened, what you can learn from it, and how you can adjust for next time. One bad month does not ruin your financial life. Quitting does.